Sun Life Zenith Bermuda

A US dollar participating whole of life savings plan, paid over two or five years — a launch briefing for professional advisers.

Up to
30%
off the first-year premium
Up to
5.0% p.a.
guaranteed interest on prepaid premiums
Projected
7.2% p.a.
return at year 60, non-guaranteed

Educational scope · Regulatory status

Educational content for licensed professional advisers, trustees, fiduciaries and private bankers. Not directed at retail clients. Not a personal recommendation or financial promotion under FSMA 2000 s.21. Capital for Life Ltd acts as an Appointed Representative Partner Practice of Forest Wealth SA (FINMA registered, Switzerland). Suitability for any individual client depends on facts, residence, and objectives not assessed here. Projected returns are non-guaranteed and based on Sun Life's assumed long-term investment returns and anticipated experience; actual values may be higher or lower than illustrated, and non-guaranteed benefits may be zero.

Plan at a glance

Policy type
Participating whole of life savings plan
Premium terms
Multi Pay 2 Year or 5 Year
Currency
US dollar
Insurer
Sun Life Bermuda Limited

Commitment

Sun Life Bermuda — Sun Life Zenith Bermuda

USD policy currency · figures from Sun Life's launch material, subject to underwriting

Minimum annual premium
US$50k
2 Year
US$25k
5 Year
Minimum initial notional amount
US$100k
2 Year
US$125k
5 Year
Launch discount on first-year premium
Up to 5%
2 Year
Up to 30%
5 Year

Discount scaled by annual premium; full table in the launch offers section. Offers run for Sun Life's launch promotion period and may be changed or withdrawn by Sun Life.

Executive summary

Guaranteed values, with bonuses on top

Sun Life has launched Zenith Bermuda, a participating whole of life savings plan for high net worth clients. It combines a Guaranteed Cash Value and Guaranteed Death Benefit with growth from non-guaranteed bonuses, projected at 7.2% a year at year 60.

It is a US dollar plan issued by Sun Life Bermuda Limited, with premiums paid over two years or five years. Coverage runs in perpetuity, so value can compound over time, and the investment strategy behind the bonuses includes an allocation to alternative assets. A Bermuda issuer adds jurisdictional diversification to the plan.

During the launch period, Sun Life is taking up to 30% off the first-year premium, and crediting guaranteed interest of up to 5.0% a year on premiums prepaid at issue. The discount applies to the first-year premium only, and the offers run for Sun Life's launch promotion period.

Why advisers use it

Liquidity for life
Cash reserve without forced asset sales
Asset for life
Defensive allocation with alternative assets inside
Protected income for life
Income stabiliser through market stress
Family for life
Whole of life cover, in perpetuity
Value layers
Guaranteed cash value and death benefit + reversionary + terminal
Jurisdiction
Bermuda issuer, regulated by the Bermuda Monetary Authority

What does the commitment look like?

A two or five year funding window for a whole of life plan

Funding is compressed into two or five years, while the contract itself runs for the whole of life.

Policy type
01
Participating whole of life
Savings plan, coverage in perpetuity
Premium structure
02
Multi Pay 2 Year or 5 Year
Annual premiums; prepayment at issue available
Minimum annual premium
03
US$50,000 (2 Year)
US$25,000 (5 Year)
Minimum initial notional amount
04
US$100,000 (2 Year)
US$125,000 (5 Year)
Policy currency
05
US dollar
Other currencies: see Sun Life's brochure
Guaranteed values
06
Cash value and death benefit
Contractual; bonuses non-guaranteed on top

Issue ages, death benefit basis and surrender terms are set out in Sun Life Bermuda Limited's product brochure and policy provisions, supplied with every illustration.

Plan value architecture

How Zenith Bermuda creates long-term value

Total plan value is built from two guaranteed foundations plus two layers of non-guaranteed participating bonuses. Sun Life projects the combined return at 7.2% a year at year 60 on its assumed long-term investment returns.

Guaranteed cash value

Guaranteed

A contractual cash value that does not depend on bonus declarations.

Guaranteed death benefit

Guaranteed

A contractual death benefit providing the plan's protection element.

Reversionary bonus

Non-guaranteed

Declared by Sun Life according to its investment returns and experience. May be zero.

Terminal bonus

Non-guaranteed

Declared by Sun Life and forming part of the plan's value when paid. May be zero.

Total plan value
4 value layers
Guaranteed base
Cash value
Guaranteed
Death benefit
Declared
Reversionary
Declared
Terminal

Two layers are contractual. Two depend on Sun Life's returns. An illustration shows both, year by year.

Planning roles

Where Sun Life Zenith fits into real client financial planning

Four recurring adviser use cases, each assigning the plan a distinct role on the client balance sheet.

01

Liquidity for Life

Cash reserve strategy
For

Balance-sheet-driven clients with illiquid assets

Role in the plan

Liquidity reserve for personal or family income needs. Accessible capital without forced asset sales or refinancing.

Why advisers use it

Supports cash-flow needs, opportunities, and contingencies. Preserves the core portfolio. Allows flexibility during property or business transitions.

Loans for Life and Property for Life →
02

Asset for Life

Diversified allocation strategy
For

Strategic asset allocation and portfolio construction

Role in the plan

Long-term, defensive allocation within a diversified portfolio. Returns driven by declared participating bonuses rather than direct market exposure, with an allocation to alternative assets inside the plan.

Why advisers use it

Reduces reliance on growth assets for stability. Balances equities, alternatives, and private investments. Smooths portfolio behaviour across market cycles.

Asset Protection & Diversification →
03

Protected Income for Life

Income stability strategy
For

Income-sensitive clients

Role in the plan

Non-market-linked income stabiliser. Liquidity buffer during periods of market stress.

Why advisers use it

Reduces sequencing risk. Avoids forced asset sales. Improves control over income timing.

Protected Income for Life →
04

Family for Life

Intergenerational planning strategy
For

Long-term estate and succession planning

Role in the plan

Whole of life planning asset, with coverage in perpetuity and a guaranteed death benefit.

Why advisers use it

Adapts to changing family circumstances. Simplifies succession. Supports long-term family governance.

Family for Life →

What is on offer during the launch period?

Launch discounts, by premium and term

During the launch period Sun Life is taking a percentage off the first-year premium, scaled by annual premium and payment term, and crediting guaranteed interest where all future premiums are prepaid at issue. The discount applies to the first-year premium only.

First-year premium discount · Multi Pay 2 Year
Annual premiumFirst-year discount
US$200,000 and above5.0%
US$100,000 – US$199,9994.5%
US$50,000 – US$99,9992.0%
First-year premium discount · Multi Pay 5 Year
Annual premiumFirst-year discount
US$1,000,000 and above30%
US$200,000 – US$999,99928%
US$100,000 – US$199,99926%
US$50,000 – US$99,99923%
US$30,000 – US$49,99918%
US$25,000 – US$29,99912%
Guaranteed interest on prepaid premiums · When all future premiums are prepaid at issue
Premium payment termGuaranteed rate
Multi Pay 2 Year5.0% p.a.
Multi Pay 5 YearYear 1: 5.0% p.a. · Years 2 to 4: 4.3% p.a.

Worked example

A Multi Pay 5 Year plan with an annual premium of US$200,000 falls in the US$200,000 to US$999,999 band, so the first-year premium is discounted by 28%: US$144,000 is payable in year 1 instead of US$200,000. Years 2 to 5 are at the full US$200,000. If all five premiums are prepaid at issue, Sun Life credits guaranteed interest on the prepaid amount at 5.0% a year in year 1 and 4.3% a year in years 2 to 4.

The discount applies to the first-year premium only. Launch offers run for Sun Life's launch promotion period and may be changed or withdrawn by Sun Life. Capital for Life confirms the offer in force at the date of each illustration.

What does 7.2% a year at year 60 mean?

A projection, not a promise

Sun Life projects a return of 7.2% a year at year 60 through the non-guaranteed Reversionary and Terminal bonuses, in addition to the guaranteed contract values. The projection is based on Sun Life's assumed long-term investment returns and anticipated experience.

Actual values may be higher or lower than illustrated, and non-guaranteed benefits may be zero. Zenith Bermuda launched on 1 October 2026, so there are no published fulfilment ratios for the plan. The only basis for a client's projected values is an official Sun Life illustration on their own figures, premium term and age.

What is and is not guaranteed
GuaranteedCash value and death benefit
GuaranteedInterest on prepaid premiums, at the published launch rates
Non-guaranteedReversionary and Terminal bonuses
Non-guaranteedThe 7.2% a year projection at year 60

Adviser Q&A

Questions advisers ask us

What is Sun Life Zenith Bermuda?

Sun Life Zenith Bermuda is a US dollar participating whole of life savings plan issued by Sun Life Bermuda Limited and launched on 1 October 2026. Premiums are paid over two years (Multi Pay 2 Year) or five years (Multi Pay 5 Year). The plan provides a Guaranteed Cash Value and a Guaranteed Death Benefit, with growth from non-guaranteed Reversionary and Terminal bonuses. Sun Life projects a return of 7.2% a year at year 60 on its assumed long-term investment returns; actual values may be higher or lower, and non-guaranteed benefits may be zero.

What is guaranteed and what is not?

The Guaranteed Cash Value and the Guaranteed Death Benefit are contractual. The Reversionary and Terminal bonuses are not guaranteed: they depend on Sun Life's investment returns and experience, and may be zero. The 7.2% a year projected return at year 60 is a projection, not a guarantee. Where all future premiums are prepaid at issue, the interest credited on the prepaid premiums is guaranteed at the rates Sun Life has published for the launch period.

What are the launch discounts?

During Sun Life's launch promotion period a discount applies to the first-year premium only, scaled by annual premium and payment term. Multi Pay 2 Year: 2.0% for US$50,000 to US$99,999, 4.5% for US$100,000 to US$199,999, 5.0% for US$200,000 and above. Multi Pay 5 Year: 12% for US$25,000 to US$29,999, 18% for US$30,000 to US$49,999, 23% for US$50,000 to US$99,999, 26% for US$100,000 to US$199,999, 28% for US$200,000 to US$999,999, 30% for US$1,000,000 and above. The offers run for Sun Life's launch promotion period and may be changed or withdrawn by Sun Life.

What interest does Sun Life pay on prepaid premiums?

Where all future premiums are prepaid at issue, Sun Life credits guaranteed interest on the prepaid amount: 5.0% a year on Multi Pay 2 Year; on Multi Pay 5 Year, 5.0% a year in year 1 and 4.3% a year in years 2 to 4. These rates apply to the launch promotion period.

What are the minimum premiums?

Multi Pay 2 Year: minimum annual premium US$50,000 and minimum initial notional amount US$100,000. Multi Pay 5 Year: minimum annual premium US$25,000 and minimum initial notional amount US$125,000.

Documentation

Supporting figures and the launch terms are in the adviser summary. Request the Sun Life product brochure and an illustration from Capital for Life.

Get an illustration — quotes@capitalforlife.com

Important regulatory information

This page is intended exclusively for professional financial advisers and is not directed at retail clients or members of the public.

Nothing on this page constitutes a personal recommendation, financial promotion, or an offer to buy or sell any insurance or investment product. Product features, premium levels, currency options, launch offers and remuneration structures are illustrative and subject to insurer terms, jurisdictional availability, and underwriting.

Participating policy values include non-guaranteed elements. Reversionary and terminal bonuses are declared at the insurer's discretion and are not guaranteed; projected returns are based on Sun Life's assumed long-term investment returns and anticipated experience, and non-guaranteed benefits may be zero. Launch offers are set by Sun Life, apply on its conditions, and may be changed or withdrawn by Sun Life.

Advisers remain responsible for assessing suitability for each client based on their residence, objectives, and circumstances, and for complying with local regulatory requirements. Sun Life Zenith Bermuda is issued by Sun Life Bermuda Limited, which is licensed and regulated by the Bermuda Monetary Authority.
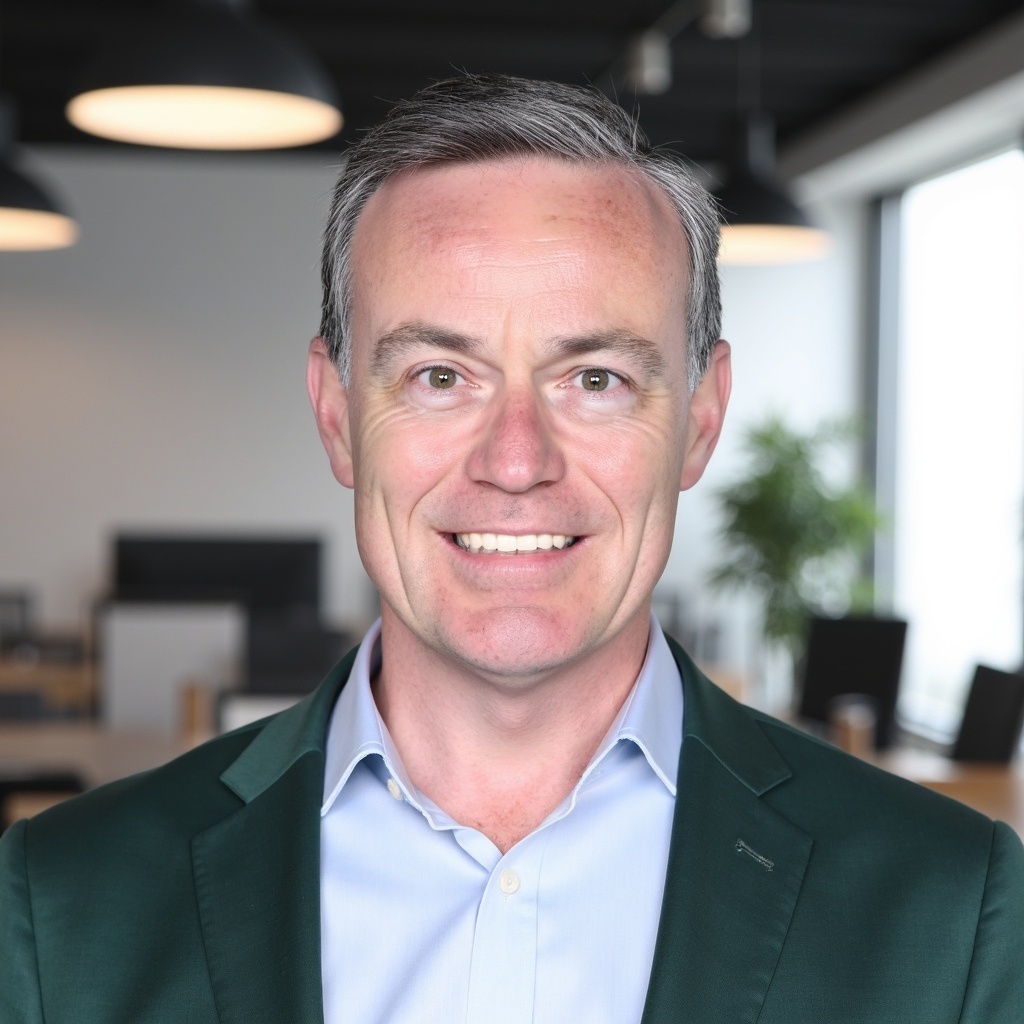
Carlton Crabbe
Carlton Crabbe
Founder and CEO, Capital for Life

Carlton Crabbe is the Founder and CEO of Capital for Life, an international life insurance advisory specialising in Indexed Universal Life and Private Placement Life Insurance for high net worth and ultra high net worth families, entrepreneurs and their advisers. With close to 30 years of specialist experience, and prior regulated roles at Barclays Private Bank and Grant Thornton, he designs cross-border IUL and PPLI structures for protection, liquidity and global estate planning across the UAE, UK, Europe, Africa, Asia and Australia.